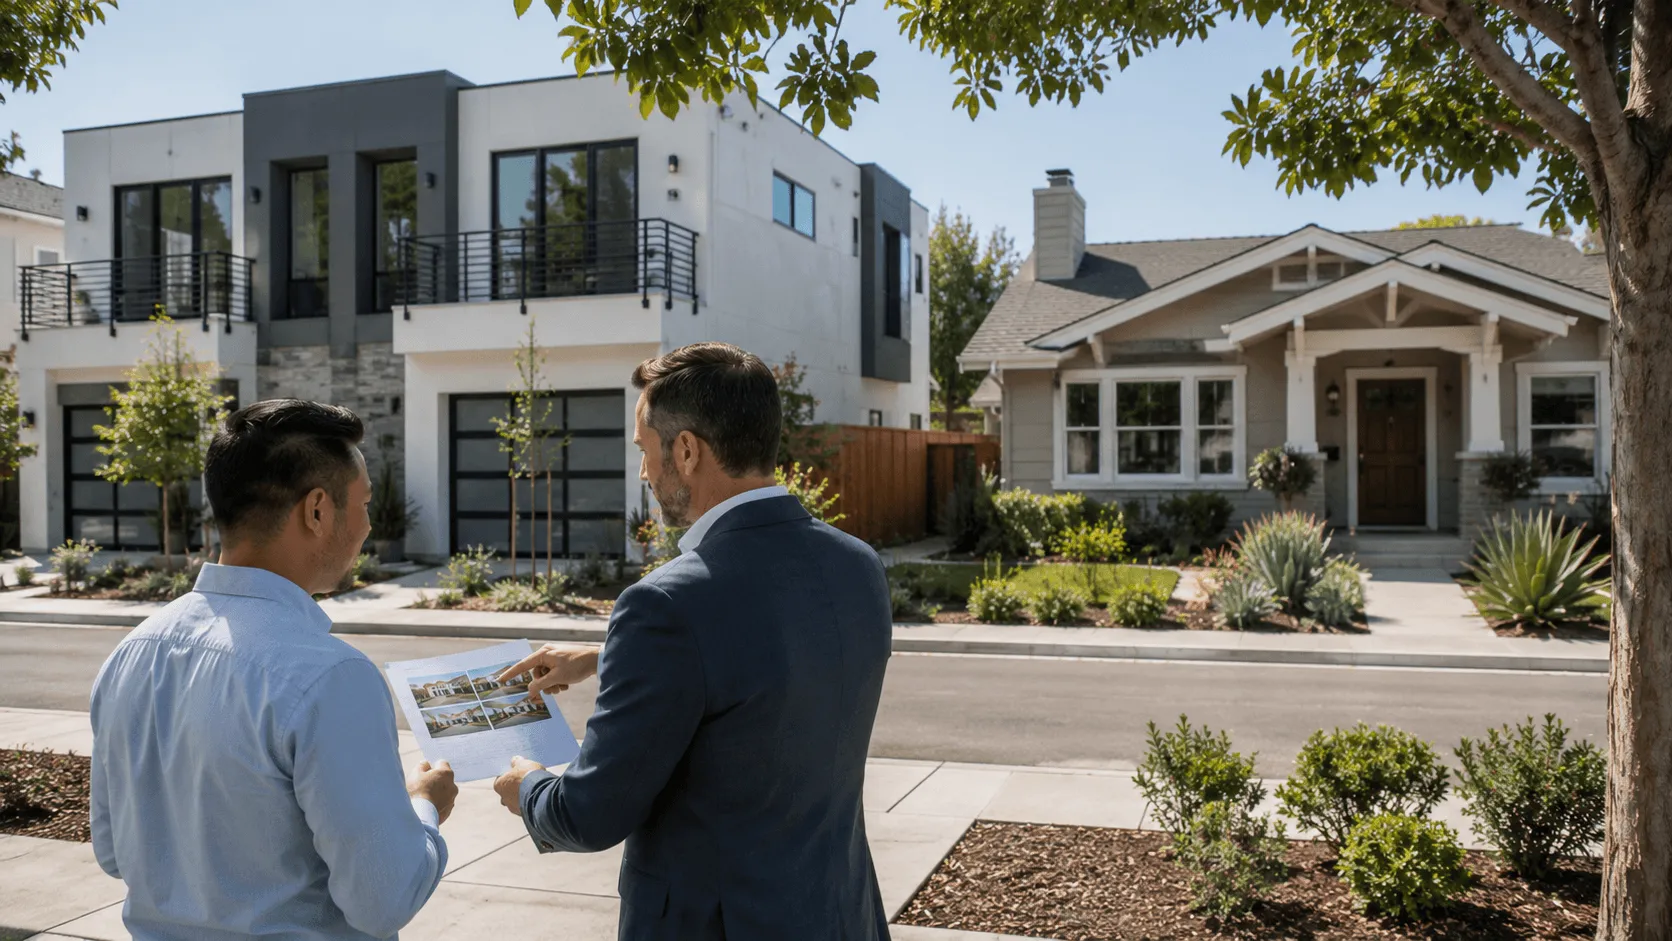

A duplex and a single-family rental can cost about the same in much of Southern California, but they work very differently. A duplex gives you two rents, owner-occupant financing with a small down payment if you live in one unit, and room to add accessory dwelling units (ADUs) under state law. A single-family home is simpler to manage, appeals to more buyers when you sell, and is exempt from California's statewide rent cap in more situations.
This guide compares the two on financing, rules, cash flow and risk, using current FHA guidelines and California housing law as of October 2026. Ali Shariat is both a Realtor and a licensed loan officer, so the worked numbers reflect how lenders underwrite these properties.
Jump To:
Quick answer
If you will live in one unit, a duplex is usually the stronger buy. You can finance it like a home with as little as 3.5% down through FHA, count part of the second unit's rent toward qualifying, and keep the option of adding ADUs later.
If you are buying a pure investment with 20–25% down, neither property type is likely to cash-flow in coastal Southern California at a 7%+ mortgage rate. The duplex typically comes closer because it brings in more rent at the same price. The single-family home is easier to run and to resell. Choose based on which risk you would rather carry.
Duplex vs. single-family at a glance
| Factor | Duplex | Single-family rental |
|---|---|---|
| Income streams | Two; one vacancy still leaves rent coming in | One; a vacancy means zero rent |
| Owner-occupant financing | FHA (3.5% down) or conventional for 2–4 units if you live in one unit | Owner-occupant loans only if you live there; investment loans otherwise |
| Rent used to qualify | 75% of the other unit's market rent (FHA, no rental history) | None while you occupy it, unless it has an ADU |
| ADU potential (state law) | Up to 2 detached ADUs plus converted space | ADU and junior ADU under single-family rules; SB 9 in single-family zones |
| Statewide rent cap (AB 1482) | Exempt only while you live in the other unit | Often exempt if not owned by a corporation or REIT, with required notice |
| Management | Two tenants, shared walls, more turnover | One tenant, fewer requests |
| Resale buyer pool | Investors and house-hackers | Owner-occupants and investors |
Financing a duplex in 2026
FHA: 3.5% down if you live there
FHA insures loans on one- to four-unit homes when at least one borrower lives in the property. Under HUD Handbook 4000.1 (last revised August 12, 2026):
- The minimum required investment is 3.5% of the adjusted value for borrowers with a credit score of 580 or higher. Scores from 500 to 579 are limited to 90% loan-to-value.
- At least one borrower must move in within 60 days of closing and intend to live there for at least one year.
- FHA charges an upfront mortgage insurance premium of 1.75% of the base loan, which can be financed. For loans over $726,200 with less than 5% down on a 30-year term, the annual premium is 0.75% for the life of the loan.
The 2026 FHA limit for a two-unit property in high-cost areas is $1,599,375 (HUD, December 2025). Orange and Los Angeles counties are at that ceiling, according to JVM Lending's county table.
How the second unit's rent helps you qualify
When you have no rental history on the property, HUD lets the lender count 75% of the lesser of the appraiser's market rent or the signed lease as income. The appraiser documents market rent on a small residential income property appraisal (Fannie Mae Form 1025). The rental income is added to your income; it does not reduce the mortgage payment.
Three- and four-unit FHA purchases must also pass a self-sufficiency test. The appraiser's market rent for every unit, minus the greater of the appraiser's vacancy and maintenance estimate or 25%, has to cover the full mortgage payment (PITI). Duplexes are not subject to this test, which is one reason two-unit properties are easier to finance with FHA.
Conventional: 5% down, with a catch
Fannie Mae's automated underwriting allows up to 95% loan-to-value on two- to four-unit primary residences, or 5% down. That applies only to purchases with conforming loan amounts. High-balance two-unit loans, common in coastal counties, still top out at 85% loan-to-value (lender bulletin summarizing Fannie Mae's DU change). For a non-owner-occupied investment, expect to put 20–25% down on either property type.
Illustrative cash-flow math
These are illustrative numbers, not market data. They show how the two property types behave under the same assumptions. Replace them with real rents, taxes and insurance quotes for the property you are considering.
Assumptions: both properties cost $1,300,000 and are bought as investments with 25% down. The loan is $975,000 on a 30-year fixed at 7.32%, the Freddie Mac average for the week of October 22, 2026. Investment property loans usually price higher, so these numbers lean optimistic. The duplex rents for $3,000 per unit and the house for $5,200 per month. Vacancy is 5%, property tax 1.1% of price, management 8% of collected rent, and capital reserves 5% of gross rent. Insurance is $3,000 a year for the duplex and $2,600 for the house. Repairs are 8% of gross rent for the duplex and 6% for the house.
| Annual figures (illustrative) | Duplex | Single-family |
|---|---|---|
| Gross scheduled rent | $72,000 | $62,400 |
| Less 5% vacancy | −$3,600 | −$3,120 |
| Operating expenses | −$32,132 | −$28,506 |
| Net operating income (NOI) | $36,268 | $30,774 |
| Cap rate (NOI ÷ price) | 2.79% | 2.37% |
| Mortgage payments | −$80,371 | −$80,371 |
| Annual cash flow | −$44,103 | −$49,597 |
| Down payment needed to break even | About 66% | About 71% |
What this shows:
- The duplex wins on income, not by enough to cash-flow. Two rents beat one at the same price, but at a 7.32% rate neither property covers its mortgage with 25% down.
- Coastal rentals are mostly appreciation and tax plays. Positive cash flow in these markets usually needs a much larger down payment, a lower price-to-rent ratio, or added units.
- Small changes swing the result. Raising the duplex rents by $300 a unit adds $7,200 a year of gross income, more than the entire difference in repairs between the two properties.
House hacking a duplex
House hacking means living in one unit and renting the other. Under the same $1,300,000 price, 7.32% rate and 1.1% tax assumptions, FHA financing works out roughly like this (illustrative):
- Down payment at 3.5%: $45,500. Base loan $1,254,500, plus $21,954 of financed upfront mortgage insurance.
- Principal and interest about $8,768, annual mortgage insurance about $784, taxes about $1,192, insurance about $250. Total: about $10,994 a month.
- Rent from the other unit at $3,000 lowers your net housing cost to about $7,994 a month. For qualifying, the lender counts 75% of that rent, or $2,250, as income.
After the one-year occupancy requirement, you can move and rent both units. You keep the low-down-payment loan you started with, and the property becomes a two-unit rental.
Adding units: ADUs and SB 9
ADUs on a duplex lot
Under state ADU law, two attached units on one lot count as a multifamily dwelling. According to the HCD ADU Handbook (March 2026):
- A lot with an existing multifamily dwelling may add detached ADUs, up to eight but not more than the number of existing units. For a duplex, that means up to two detached ADUs.
- Cities must allow at least one ADU created from non-livable space such as a garage, storage room or attic, and up to 25% of the existing unit count.
- A duplex does not qualify for a junior ADU, which is limited to single-family homes.
- These ADUs, if rented, must be rented for terms longer than 30 days, so they can't be used as short-term rentals.
A duplex that can add two ADUs becomes a four-unit income property on one lot. Get a site review before you count on it.
SB 9 on single-family lots
SB 9 lets owners in single-family zones build up to two primary units on a lot, split the lot into two, or both. Cities must allow each unit to be at least 800 square feet (HCD SB 9 fact sheet). For lot splits, the owner signs an affidavit of intent to live in one of the units as a principal residence for three years. Units created under SB 9 can't be rented for 30 days or less.
This is where single-family homes have an edge. A house on a large lot in a single-family zone can sometimes become a duplex or two lots. Most duplexes already sit in multifamily zones, where SB 9 doesn't apply.
Rent control rules that differ
California's Tenant Protection Act (AB 1482) caps annual rent increases on covered units at the lesser of 5% plus local CPI or 10% (San Mateo County summary). Exemptions differ by property type:
- Duplex: exempt only when the owner lives in the other unit. Once you move out and rent both units, the cap and just-cause rules generally apply, unless the building was placed in service within the last 15 years.
- Single-family home or condo: exempt if not owned by a corporation or REIT and the tenant receives the required written exemption notice.
Local rules can be stricter. In the City of Los Angeles, the Rent Stabilization Ordinance generally covers properties with two or more units built on or before October 1, 1978, which includes many older duplexes. Check the city's rules before you underwrite rent growth.
Management, vacancy and resale
- Vacancy risk: a duplex with one empty unit still collects half its rent. A vacant house collects nothing, so hold larger cash reserves for a single-family rental.
- Turnover and wear: two tenants mean twice the move-outs, and shared walls create noise complaints. Budget for more frequent turnover costs.
- Resale: a single-family home can be sold to owner-occupants, the largest buyer pool. A duplex sells to investors and house-hackers and is valued partly on its rents, so a below-market lease can lower its price.
Location still matters more than property type. Older duplexes are more common in established neighborhoods of cities like Santa Ana and Anaheim than in master-planned communities. For a broader comparison that includes larger buildings, see multifamily vs. single-family rentals.
How to choose
- Decide whether you will live there. If yes, price out an FHA or 5%-down conventional duplex first.
- Get real rent comps for each unit and the house, and run both through the table above with your numbers.
- Check zoning and the lot for ADU or SB 9 potential. Added units are often what makes the math work.
- Check rent control status, both AB 1482 and any city ordinance, and any existing leases.
- Stress-test vacancy and repairs. If one bad year would force a sale, the deal is too thin.
Key takeaways
- FHA allows 3.5% down on a duplex if you move in within 60 days and live there at least a year. The 2026 two-unit limit in Orange and Los Angeles counties is $1,599,375.
- Lenders can count 75% of the other unit's market rent toward qualifying. Only three- and four-unit FHA purchases face the self-sufficiency test.
- At 7.32% with 25% down, the illustrative duplex and house both run negative, but the duplex loses less.
- State law allows up to two detached ADUs on a duplex lot. SB 9 favors single-family lots in single-family zones.
- A rented-out duplex is generally covered by AB 1482's rent cap. A single-family rental owned by an individual is often exempt, with notice.
FAQs
Is a duplex a better investment than a single-family home in California?
For an owner who lives in one unit, a duplex is usually better: low-down-payment financing, rent from the second unit, and room for ADUs. For a pure investor, a duplex typically produces more rent at the same price. A single-family home is easier to manage, has a larger resale market, and is more often exempt from the statewide rent cap.
Can I buy a duplex with an FHA loan?
Yes. FHA insures one- to four-unit homes when a borrower lives in one unit. The minimum down payment is 3.5% with a credit score of 580 or higher, and you must move in within 60 days and intend to stay at least one year. The 2026 two-unit limit is $1,599,375 in Orange and Los Angeles counties.
Does rent from the other unit count as income for the mortgage?
Yes. With no rental history on the property, FHA lets the lender count 75% of the lesser of the appraiser's market rent or the lease rent as income. Conventional lenders use a similar 75% approach.
Can I add an ADU to a duplex in California?
Generally, yes. State law treats a duplex as a multifamily dwelling, which allows up to two detached ADUs plus at least one ADU converted from non-livable space such as a garage. These ADUs must be rented for more than 30 days. Site conditions and local objective standards still apply.
Is a duplex subject to rent control in California?
Under AB 1482, a duplex is exempt only while the owner lives in the other unit. A fully rented duplex is generally covered unless it was built within the last 15 years. Older duplexes in cities like Los Angeles may also fall under local rent stabilization.
Comparing a duplex with a single-family rental? Ali Shariat can pull rent comps, check ADU potential, and pre-qualify you for FHA or conventional financing in one conversation. Contact Ali or call (949) 818-1000.